Institutional capital is still willing to make billion-dollar bets on commercial real estate—but it is being highly selective about where it places that money.
That point was underscored on November 2, when Brookfield Asset Management and Canada Pension Plan Investment Board completed their acquisition of LXP Industrial Trust in an all-cash transaction valued at approximately $5.2 billion, including net debt and preferred equity.
LXP shareholders received $61.20 per share, and the company’s stock stopped trading publicly after the closing. LXP is now privately held and will be integrated into Brookfield’s global logistics platform.
The deal is more than a large REIT take-private. It is a useful case study in how major investors are approaching commercial real estate in late 2026: favoring properties with visible income, long-term demand drivers, and operational scale rather than relying solely on broad market recovery.
What Brookfield and CPP bought
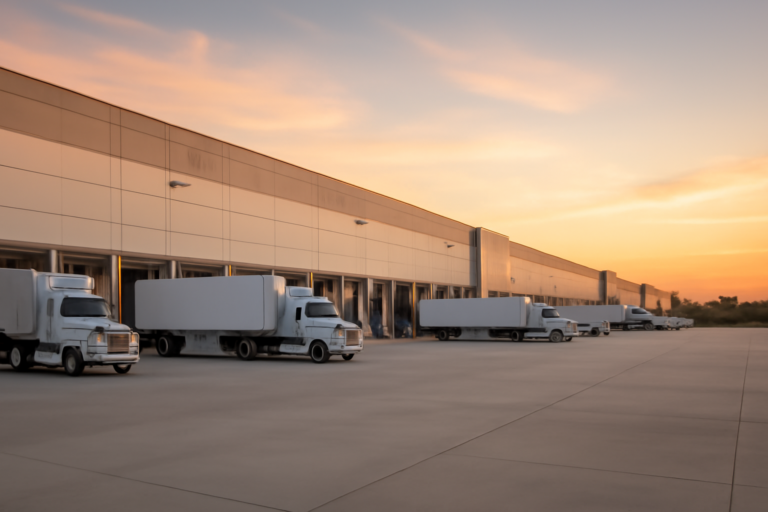
LXP’s portfolio consists of 107 industrial properties totaling approximately 52 million square feet across markets in the Sunbelt and Midwest. The company has focused on Class A warehouse and distribution facilities, including properties serving modern logistics and manufacturing users.
Brookfield said the portfolio benefits from strong occupancy and long-duration leases. The assets will be added to Brookfield’s existing global logistics platform, which spans more than 255 million square feet across more than 850 properties in 20 countries.
That existing platform matters. A large portfolio can create advantages that are difficult for smaller owners to replicate, including:
- Better access to institutional debt and equity capital
- More efficient property management and leasing operations
- Greater ability to sell, recapitalize, or reposition individual assets
- More data for underwriting tenant demand and operating performance
- The ability to pursue portfolio-level transactions rather than isolated property sales
For Brookfield and CPP, the acquisition is therefore not simply a bet on 107 individual buildings. It is also a bet on the value of owning a scaled logistics platform at a time when industrial real estate is becoming more operationally complex.
Why this deal matters now
Industrial real estate remains one of the most institutionally favored parts of commercial property, but that does not mean every warehouse is equally attractive.
The market has changed since the rapid rent-growth period of 2021 and 2022. New supply has entered many logistics markets, leasing velocity has become more uneven, and tenants are scrutinizing occupancy costs more carefully. Higher interest rates have also made it harder to justify aggressive pricing based only on future rent growth.
Against that backdrop, the LXP transaction highlights the attributes that can still command institutional attention:
1. Durable in-place cash flow
Long leases provide income visibility. That can be particularly valuable when capital markets are volatile and refinancing costs remain a concern.
A property with contractual rent escalations and a creditworthy tenant base may not deliver the highest immediate upside, but it can offer more predictable cash flow than an asset dependent on rapid lease-up or aggressive mark-to-market assumptions.
2. Modern logistics functionality
Large institutional buyers are not purchasing industrial space simply because it is labeled “warehouse.” Building age, clear heights, loading configuration, truck access, power availability, location, and tenant-specific functionality all affect long-term competitiveness.
Modern buildings in strategic distribution locations are more likely to remain relevant as tenants redesign supply chains, expand regional fulfillment networks, or support domestic manufacturing.
3. Sunbelt and Midwest exposure
LXP’s concentration in Sunbelt and Midwest markets aligns with several long-term investment themes, including population growth, manufacturing investment, logistics expansion, and shifting distribution patterns.
Those themes are not automatic guarantees of performance. Local supply pipelines, labor availability, transportation infrastructure, taxes, and tenant concentration still matter. But institutional buyers appear willing to pay for exposure to markets where those fundamentals are viewed as supportive over a multiyear holding period.
The signal for passive investors
Passive investors should not interpret the LXP deal as evidence that industrial real estate is universally safe or that every large warehouse portfolio is attractively priced.
The more useful takeaway is that the market is rewarding quality differentiation. Institutional capital is still active, but its preferences are becoming clearer. Investors are looking for assets that can preserve occupancy and cash flow through different interest-rate and economic environments.
That has several implications for passive investment decisions.
Underwrite the lease, not just the property type
An industrial investment can look attractive at the sector level while carrying meaningful property-specific risk. Review tenant credit, lease expiration schedules, renewal probabilities, rent escalations, options, and any near-term capital obligations.
A long lease is not automatically a strong lease. Investors should understand who pays operating expenses, how much contractual rent growth is embedded, and whether the tenant has realistic alternatives when the lease expires.
Pay attention to rollover concentration
A portfolio may report high occupancy while still facing substantial leasing risk if several large tenants expire within the same period.
Passive investors should ask:
- What percentage of rent expires in the next three to five years?
- Are the largest tenants investment-grade or financially stable?
- How much downtime would be required if a major tenant leaves?
- Are replacement rents supported by actual recent transactions?
- Does the business plan assume tenant improvements or leasing commissions that are not fully reserved?
Do not confuse scale with insulation
Brookfield and CPP have the resources to manage portfolio-level challenges, but scale does not eliminate market risk. Industrial owners can still face tenant bankruptcies, rent resets, rising insurance costs, property taxes, obsolescence, and oversupply in specific submarkets.
For passive investors, the quality of the sponsor and operating platform remains important—but it should complement, not replace, property-level underwriting.
What to watch next
The LXP acquisition could be an early indicator of more consolidation among publicly traded real estate companies and private portfolios.
Several conditions would support additional transactions:
- Public-market valuations remain below the perceived value of underlying real estate
- Interest-rate uncertainty moderates enough to improve financing visibility
- Institutional investors continue seeking scale in logistics and other preferred sectors
- Owners face refinancing or portfolio simplification decisions
- Buyers can identify assets with durable income at a reasonable basis
However, investors should also watch whether future deals become more selective than broad. The strongest transactions are likely to center on assets with durable leases, modern specifications, and favorable market positioning—not simply on distressed properties or large square footage totals.
The transaction’s structure also matters. Brookfield and CPP did not acquire LXP through a highly speculative development platform or a turnaround dependent on immediate rent growth. They acquired a scaled portfolio designed around existing industrial cash flows and long-term logistics demand.
That is a meaningful distinction in the current environment.
The bottom line
The completed LXP acquisition shows that institutional conviction in commercial real estate has not disappeared. It has narrowed.
Brookfield and CPP Investments committed approximately $5.2 billion to a portfolio of 107 industrial properties because the assets offer scale, logistics relevance, geographic exposure, and contractual income characteristics that can support a long-term ownership strategy.
For passive investors, the lesson is straightforward: sector labels are not enough. The most resilient opportunities are likely to be those combining strong real estate fundamentals with conservative leverage, credible sponsorship, durable tenant demand, and a clear plan for managing lease rollover.
Industrial real estate may remain a favored CRE sector, but the next phase will likely reward underwriting discipline more than simple exposure.