The office recovery is becoming easier to see—and harder to generalize
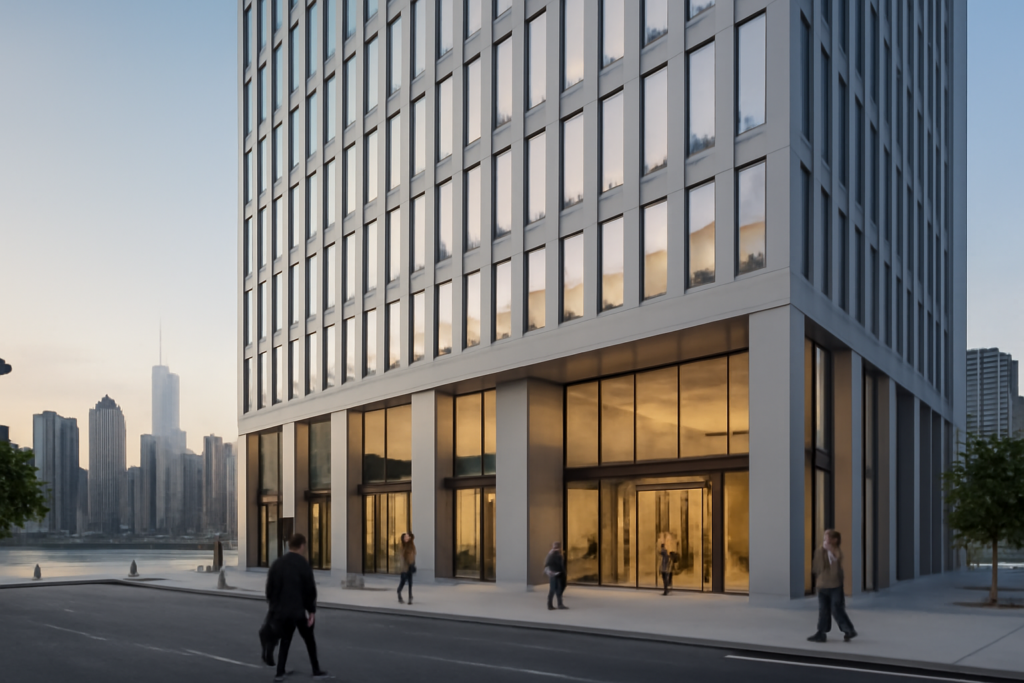
Oppenheimer & Co. has signed a lease for approximately 220,000 square feet at RXR’s 32 Old Slip in Lower Manhattan. The investment bank and wealth management firm plans to occupy six floors of the 36-story, roughly 1.1 million-square-foot tower, with a phased move expected to begin in the first quarter of 2028.
Oppenheimer is relocating its headquarters from its current Lower Manhattan space. The commitment is expected to retain more than 1,000 New York City jobs, and Oppenheimer and RXR plan to invest approximately $66 million in the relocation, renovation, and tenant build-out. Empire State Development is also providing a $3.2 million capital grant.
The lease is notable because it is large, long-term, and located in a submarket that continues to carry substantial vacancy. It is not evidence that the entire office sector has recovered. It is evidence that the best-positioned buildings can still win meaningful tenants—even in a difficult market.
Why this transaction matters
The headline square footage is important, but the underlying structure of the deal is more useful for investors.
First, this is a headquarters relocation rather than a small satellite-office expansion. Oppenheimer is concentrating employees across multiple floors and investing in a workplace designed around its operations, technology, and client interactions. That type of commitment generally reflects a longer planning horizon than a short-term lease extension or incremental expansion.
Second, the building is not new. 32 Old Slip was completed in 1987, but RXR is pairing the lease with a significant renovation and fit-out program. The project will be led by Gensler and is intended to modernize the space for Oppenheimer’s use.
That distinction matters. Office investors do not necessarily need newly constructed buildings to compete for tenants. They do need buildings that can deliver current standards for infrastructure, amenities, efficiency, power, security, and workplace design. Older properties may remain viable, but only if ownership is willing and able to fund the required upgrades.
Third, the lease provides a durable occupancy win for the landlord. A major financial-services tenant occupying six floors gives RXR a stronger income base and a more credible leasing story for the remaining space. It may also improve the building’s position with lenders and future buyers, although the deal’s financial terms were not publicly disclosed.
Lower Manhattan is improving—but still has a large gap to close
Lower Manhattan has lagged Midtown and Midtown South since the pandemic, partly because of its large inventory of older Class B and Class C office buildings. The submarket also has a high vacancy rate relative to more competitive parts of Manhattan.
Bisnow, citing Cushman & Wakefield, reported that the western portion of the Financial District had a 26.7% vacancy rate at the end of the third quarter. That figure is a reminder that one major lease does not change the market’s fundamentals overnight.
At the same time, leasing activity has begun to improve. Reporting cited by Bisnow indicated that tenants signed approximately 4 million square feet south of Canal Street during the first half of 2026, while asking rents increased from the prior year. Other market measures also point to improving momentum across Manhattan, although vacancy remains elevated and different brokerage firms use different definitions for availability and vacancy.
The appropriate conclusion is not that Lower Manhattan is “back.” The more defensible conclusion is that demand is becoming more concentrated in buildings and locations that can offer a compelling reason to move.
What passive investors should take from the deal
1. Building quality is becoming a financing variable
For office owners, capital spending is no longer just a leasing expense. It increasingly affects a property’s value, liquidity, and ability to refinance.
A building with outdated mechanical systems, limited power capacity, inefficient layouts, or weak amenities may require substantial investment before it can compete for high-credit tenants. If ownership cannot fund that work, the property may lose tenants, suffer rising concessions, and face lower cash flow at loan maturity.
By contrast, a well-capitalized owner can use a major lease to justify targeted investment. The Oppenheimer transaction illustrates this model: the tenant receives a modern headquarters, while the landlord converts capital spending into a long-term occupancy commitment.
For passive investors evaluating an office fund or syndication, the key questions are practical:
- How much tenant-improvement and leasing-commission capital is required over the hold period?
- Does the sponsor have enough liquidity to fund upgrades without excessive new debt?
- Are building systems and power capacity adequate for the target tenant profile?
- Is the property competing against newer buildings on rent, or on differentiated functionality?
2. Tenant credit matters more than headline occupancy
A property can report high occupancy and still have weak income quality if leases are short, tenants are financially fragile, or rents are materially below market.
A large commitment from an established financial-services firm does not eliminate operating risk, but it gives investors a stronger form of cash-flow visibility than a collection of small tenants with uncertain renewal prospects. For office assets, lease term, tenant credit, renewal probability, and capital obligations should be analyzed together.
Passive investors should also look beyond the tenant’s name. A strong tenant may still demand expensive improvements, rent abatements, and relocation allowances. The value of a lease depends on the net economics after those costs—not simply on the square footage occupied.
3. Selective office recovery creates wider dispersion
The market is increasingly splitting into several categories:
- Buildings with modern infrastructure and strong locations that can attract large tenants.
- Older buildings that can compete after substantial repositioning.
- Properties with functional limitations that may require conversion, redevelopment, or a deeply discounted basis.
That dispersion makes broad office-market statistics less useful for investment decisions. A falling citywide vacancy rate can coexist with severe distress in a specific submarket or building class. Conversely, a high-vacancy market can still produce attractive outcomes for owners who acquire the right asset, invest intelligently, and secure durable tenancy.
What to watch next
The next question is whether Oppenheimer’s deal becomes part of a broader pattern or remains an isolated large transaction.
Investors should monitor several indicators:
- Large-block leasing. More headquarters relocations and 100,000-square-foot-plus commitments would suggest that companies are moving from experimentation to longer-term workplace decisions.
- Flight to quality. Continued leasing at renovated older towers would show that tenants value building functionality more than construction vintage alone.
- Concession levels. Strong leasing volume is less meaningful if free rent and tenant-improvement packages continue rising faster than effective rents.
- Loan maturities. Even improving occupancy may not solve refinancing problems if property-level cash flow remains below debt-service requirements.
- Conversion economics. Buildings that cannot attract tenants may face pressure to convert to residential, hospitality, education, or other uses—but those strategies require zoning flexibility, capital, and time.
For passive commercial real estate investors, the main lesson is straightforward: office recovery is not arriving as a broad tide that lifts every asset. It is emerging through specific tenants, specific buildings, and specific capital plans.
Oppenheimer’s planned move to 32 Old Slip is a meaningful positive signal for Lower Manhattan. But the transaction is most valuable as a framework for underwriting. The winners will likely be properties where tenant demand, building quality, ownership liquidity, and lease economics reinforce one another.