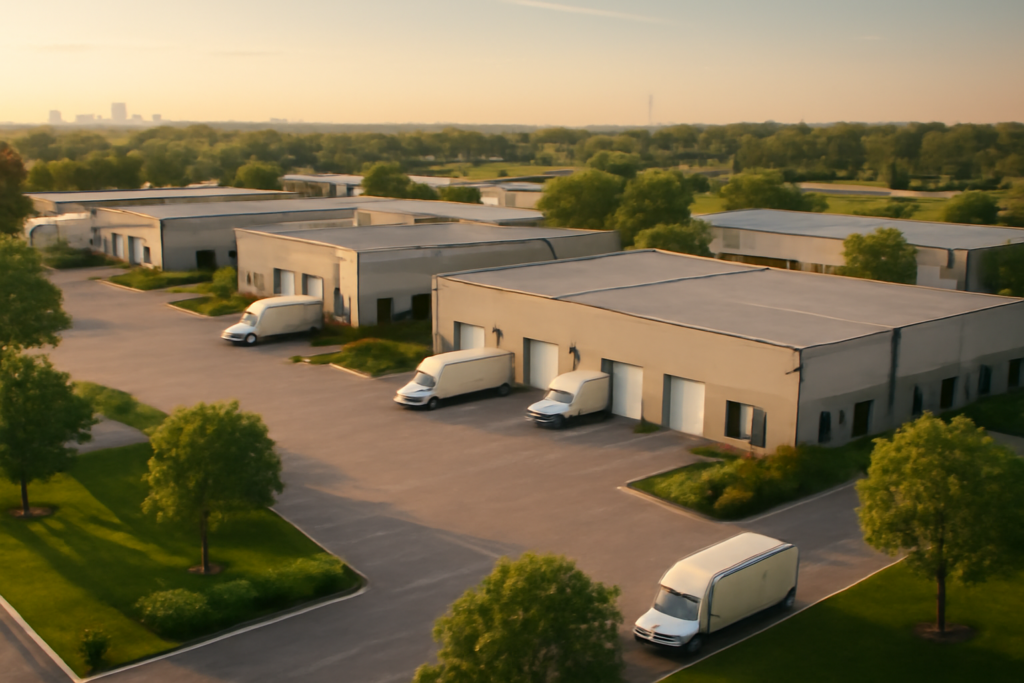
The industrial market is becoming more selective
Industrial real estate remains one of the most closely watched sectors in commercial property, but investors are no longer treating every warehouse as interchangeable.
That distinction was visible in a transaction announced in early September: MLG Capital acquired a 1.53 million-square-foot portfolio of 29 light-industrial buildings in Indianapolis. The portfolio is located in the Park 100 and Park Fletcher industrial parks, two established infill nodes in the city’s northwest and southwest submarkets.
The purchase price was not disclosed. However, the portfolio was reported to be 94% leased to 158 tenants, providing an important clue about the investment thesis. This was not a single-tenant logistics bet or a concentrated wager on one large distribution facility. It was an aggregation of smaller industrial properties serving a broad tenant base.
For passive investors, that structure matters.
What happened in Indianapolis
Colliers arranged the sale of the Indianapolis West Infill Industrial Portfolio to MLG Capital. The buyer acquired the assets for its MLG Legacy Fund alongside 1031 exchange investors.
The portfolio contains approximately 52,900 square feet per building on average. That places it firmly in the multi-tenant, light-industrial category rather than the large-format distribution segment that has dominated much of the industrial investment conversation in recent years.
The properties are positioned near Indianapolis’ interstate network and Indianapolis International Airport. The locations also benefit from being inside established industrial parks rather than in emerging areas dependent on future infrastructure or speculative development.
Private Real Estate Daily reported that the portfolio has 158 tenants across national, regional, and local companies. That tenant diversity reduces the immediate impact of any single lease expiration, although it also creates a more operationally intensive ownership model than a single-user warehouse.
The deal is meaningful not because it was the largest industrial transaction of the year, but because it illustrates where institutional buyers appear willing to commit capital in a market where pricing, supply, and tenant demand have become more uneven.
Why small-bay industrial is attracting attention
Small-bay industrial properties generally serve businesses that need space for local distribution, light manufacturing, contractor operations, service businesses, equipment storage, or last-mile activity.
These tenants may not require hundreds of thousands of square feet, but they often need functional space in locations close to customers, labor, highways, and suppliers. That can make infill buildings difficult to replace when land becomes scarce or zoning limits new construction.
Colliers’ Indianapolis research has pointed to a 6.5% industrial vacancy rate in the market at the end of the second quarter of 2026. The firm also reported that tenant demand was rebounding toward levels seen before the recent slowdown.
That does not mean every industrial asset is performing equally well. Newer bulk warehouses can face competition from substantial development pipelines, particularly when speculative projects deliver before being fully leased. Older small-bay facilities may have different challenges, including lower clear heights, limited loading capacity, and higher maintenance requirements.
But the demand profile can be more diversified. A 29-building portfolio with 158 tenants is exposed to many individual business decisions rather than one major occupier’s distribution strategy.
For investors, the key takeaway is not simply “buy industrial.” It is to distinguish between:
- Infill and peripheral locations
- Small-bay and large-format facilities
- Diversified and concentrated tenant rosters
- Existing cash flow and speculative development exposure
- Functional buildings and obsolete product
Diversification helps—but does not eliminate risk
A diversified tenant base can reduce concentration risk, but it does not remove leasing risk.
Multi-tenant industrial properties typically require more leasing decisions, more tenant improvements, and more frequent capital work. If suites are relatively small, operating costs can also rise because ownership is handling many leases, turnovers, and service requests.
Passive investors should therefore look beyond occupancy. A 94% leased portfolio may still have meaningful rollover exposure if a large portion of leases expire over the next two or three years. Investors should also examine whether in-place rents are below market, near market, or already fully marked to current conditions.
Other questions include:
- How much of the rent comes from the largest tenants?
- What is the weighted-average remaining lease term?
- Are tenants paying for taxes, insurance, and maintenance?
- How much capital is required for roofs, paving, loading areas, and HVAC systems?
- Are the buildings suitable for modern users, or are they dependent on older industrial demand?
- How much new small-bay supply is likely to enter the submarket?
The answers can materially change the risk profile of an otherwise attractive portfolio.
Indianapolis offers a useful market test
Indianapolis is an important logistics market because of its central U.S. location, interstate connectivity, manufacturing base, and proximity to a major air-freight hub.
The market also demonstrates why local supply conditions matter. A national industrial strategy may look attractive on paper, but the performance of a specific portfolio will depend on submarket vacancy, competing deliveries, tenant demand, labor availability, and achievable rents.
Park 100 and Park Fletcher are established industrial locations, which can provide advantages over a new project in a less proven corridor. Existing infrastructure, transportation access, and a history of tenant demand may help support leasing activity through different economic cycles.
Still, investors should not assume that a Midwest location automatically means lower risk. Indianapolis has also seen significant industrial development and large lease transactions. The question is whether new supply competes directly with the acquired properties or serves a different tenant segment.
That distinction is especially important for small-bay assets. A new million-square-foot distribution center may not be a direct substitute for a 20,000- or 40,000-square-foot industrial suite, but it can affect land pricing, labor competition, and the broader balance between supply and demand.
What passive investors should watch next
The Indianapolis transaction points to several trends worth monitoring across the industrial sector.
1. Institutional aggregation
Investors may continue assembling fragmented portfolios of smaller industrial assets. Aggregation can create operating efficiencies, improve reporting, and make a collection of individual properties more attractive to institutional capital.
2. Occupancy versus rent growth
High occupancy is helpful, but it is not enough. Investors should track whether landlords are achieving rent increases, merely maintaining occupancy through concessions, or accepting shorter leases to keep buildings full.
3. New construction by product type
The industrial supply pipeline should be analyzed by building size and configuration. A wave of large bulk deliveries may not directly compete with small-bay assets, while new flex and light-industrial projects could pressure them more directly.
4. Tenant diversification
Portfolios with many tenants can reduce single-tenant concentration, but the tenant mix still matters. A collection of small companies tied to cyclical industries may be less defensive than the raw tenant count suggests.
5. Financing discipline
Industrial fundamentals do not eliminate the need for conservative leverage. Debt service, refinancing terms, interest-rate caps, and required capital expenditures will determine how much of the property’s operating performance reaches equity investors.
The broader lesson
MLG Capital’s Indianapolis acquisition is a reminder that the strongest industrial opportunities may be increasingly specific rather than broadly sector-wide.
Investors are still interested in industrial real estate, but the focus is shifting toward assets with durable locations, diversified tenancy, functional layouts, and a clear role in local supply chains. For passive investors evaluating a fund or syndication, those characteristics may be more important than simply seeing “industrial” in the offering summary.
The opportunity is not risk-free. Small-bay properties demand active management, and undisclosed pricing makes it impossible to judge the transaction’s valuation or going-in yield. But the deal provides a useful market signal: in a more selective capital environment, established infill industrial portfolios with broad tenant bases can still attract institutional buyers.
That is the part of the industrial market passive investors should continue watching—not just how much warehouse space is being built, but which buildings tenants can realistically replace.